India’s Foreign Policy Meets Foreign Money: How IFS & IRS Officers Shape India’s Global Strategy
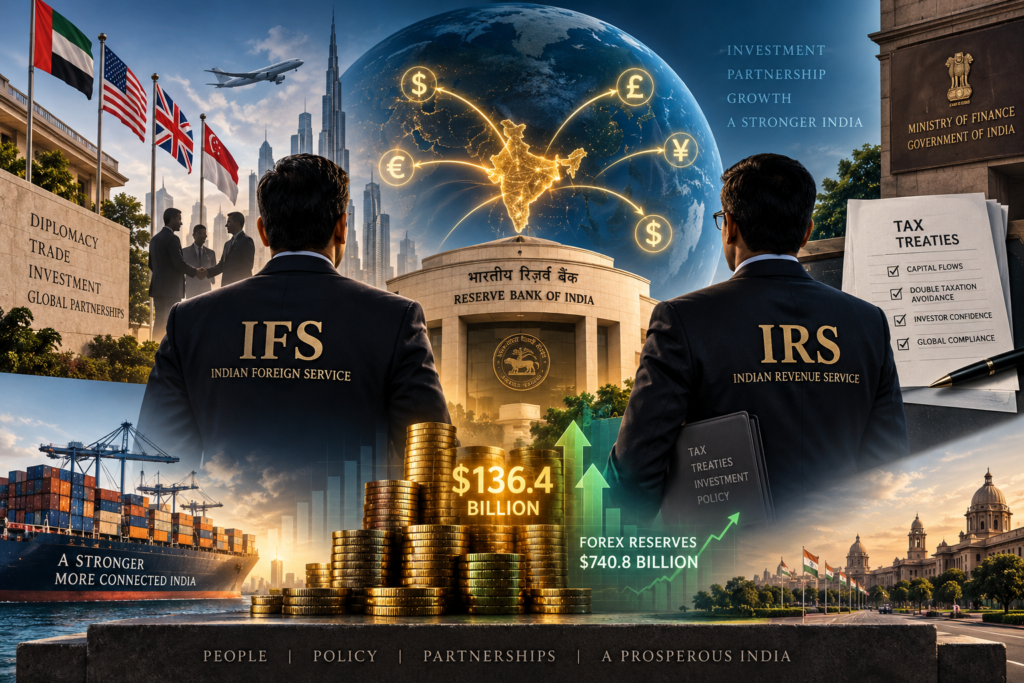
Fresh foreign-currency inflows of $136.4 billion have poured in through the Reserve Bank of India’s special swap facilities. Most of it—over $127 billion—came from FCNR(B) deposits by non-resident Indians, with smaller but useful chunks from external commercial borrowings and overseas foreign-currency borrowings. These inflows helped push India’s forex reserves past earlier peaks to $729.3 billion in late August, and then on to a new record of around $740.8 billion by the end of the month. The RBI has been active in the market, using the buffer to steady the rupee after months of pressure linked to higher oil prices and global volatility. This is not just an economic headline. It sits right at the meeting point of money and diplomacy. India’s ability to attract and manage these dollars depends on more than interest rates or swap windows. It depends on the people who sit in embassies, negotiate tax treaties, explain India’s rules to foreign investors, and keep the conversation going with governments and businesses abroad. That is where Indian Foreign Service (IFS) officers and Indian Revenue Service (IRS) officers come in. IFS officers are the ones on the ground. In missions from Dubai to London to Singapore, they spend a large part of their time on economic work these days. They track investment interest, help Indian companies navigate local rules, and quietly push for better access for Indian goods and services. When non-resident Indians decide to park money in FCNR(B) deposits, part of the comfort comes from the steady messaging that comes out of these missions: India is open for business, the rules are clearer than they used to be, and the government is serious about stability. Economic diplomacy is no longer a side job for ambassadors. It is core work. Officers report market sentiment back to Delhi, flag opportunities, and help resolve the small friction points that can stop a deal or an investment. IRS officers play a quieter but equally important role. Foreign money does not move only on sentiment. It moves on clarity about tax. Double taxation avoidance agreements, transfer pricing rules, the treatment of interest income on NRI deposits, capital gains on government securities—these details decide whether money stays or leaves. IRS officers in the Central Board of Direct Taxes and in the international taxation units negotiate and interpret these rules. When the government and RBI recently made Indian government bonds more attractive by expanding access and adjusting tax treatment, the technical work behind those decisions involved revenue officers who understand both Indian law and what foreign funds actually worry about. Without that groundwork, the $136.4 billion would have been harder to attract. The two services do not work in isolation. In many capitals, the commercial sections of embassies now coordinate closely with tax experts back home and with the finance ministry. An IFS officer explaining India’s bond market to a sovereign wealth fund will often need a clear answer on withholding tax or capital gains treatment. That answer comes from the revenue side. When Indian public sector units raise overseas borrowings under the RBI’s concessional facilities, the tax and regulatory clarity that IRS officers help provide reduces the cost of those funds. The result is a smoother pipeline for foreign currency to enter the system. This coordination has become more visible in the last few years. India’s foreign policy has shifted toward pragmatic economic engagement. Energy security, supply-chain resilience, technology partnerships, and capital inflows are treated as strategic priorities, not secondary concerns. IFS officers are expected to deliver on trade and investment outcomes alongside traditional political work. Performance is increasingly measured by concrete results—market access opened, investments facilitated, disputes resolved. At the same time, the revenue department has had to modernise its approach to international taxation so that India remains competitive without giving away the store. The recent inflows show what happens when the pieces fit. The RBI’s swap facility removed currency risk for banks and depositors. The policy framework made the returns attractive. And the diplomatic and tax machinery made the overall environment credible. Reserves are now at record levels. The rupee has found some support. Import cover remains comfortable. These are not abstract achievements. They give India room to manoeuvre when oil prices spike or when global risk appetite suddenly changes. Of course, the story is not finished. The bulk of the $136.4 billion is deposit money that will eventually mature. Sustaining confidence will require continued policy consistency and clean execution on the ground. IFS officers will keep explaining India’s position in a noisy world. IRS officers will keep refining the tax framework so that legitimate capital feels welcome and aggressive avoidance is checked. Both groups operate under political direction, but the day-to-day craft of making India an easier place to put money—and keep it—belongs to them. Next time you see a headline about forex reserves or the rupee, remember the quieter work behind it. Diplomats in distant capitals and tax officers in Delhi are part of the same effort. Foreign policy and foreign money are no longer separate files. They meet every day in the decisions these officers help shape. And right now, those decisions are showing up in the numbers. Sources: RBI data and statements on forex inflows and reserves (August–September 2026 reporting)CNBC-TV18, Financial Express, Economic Times, Business Standard, Reuters, Bloomberg coverage of the $136.4 billion mobilisation and reserve levelsMinistry of External Affairs descriptions of IFS functions and economic diplomacy rolesPublic reporting on coordination between economic and revenue wings of government on capital inflows and tax treatment of foreign investment @Rohit Manral